Language

ABA Routing 253279196

Mortgage Loans

Save money on your next mortgage.

Many mortgage lenders require a large down payment to avoid Private Mortgage Insurance (PMI). We don’t. Our adjustable-rate mortgages do not require PMI unless you borrow more than 90% loan to value. That means you keep more money for moving, furnishing–whatever you need to make that house yours.

5/1 ARM Loans As Low As

5.625

%

Rate fixed for 5 years

Mortgage types we offer

Two-Year Adjustable Rate Mortgage (ARM)

Borrow up to 97%* loan
to value

PMI not required if LTV is 90% or less

Initial rate, principal, and interest payments fixed for the first 2 years

After 2 years, the rate can change but cannot change more than 1% up or down

Rate cannot change more than 8% up or down for the life of the loan (from the initial rate)

Five/One Adjustable Rate Mortgage (ARM)

Borrow up to 97%* loan
to value

PMI not required if LTV is 90% or less

Initial rate, principal, and interest payments fixed for the first 5 years

After 5 years, the rate can change but cannot change more than 1% up or down

Rate cannot change more than 8% up or down for the life of the loan (from the initial rate)

Fixed-Rate

Borrow up to 97%* loan
to value

PMI not required if LTV is 90% or less

Choose a 10 to 30 or 30-year term, rate stays fixed throughout the term

Rate will not change

gray x icon with transparent background

Other Mortgage Offerings

Jumbo

Unimproved

Primary

Secondary

Investment Property

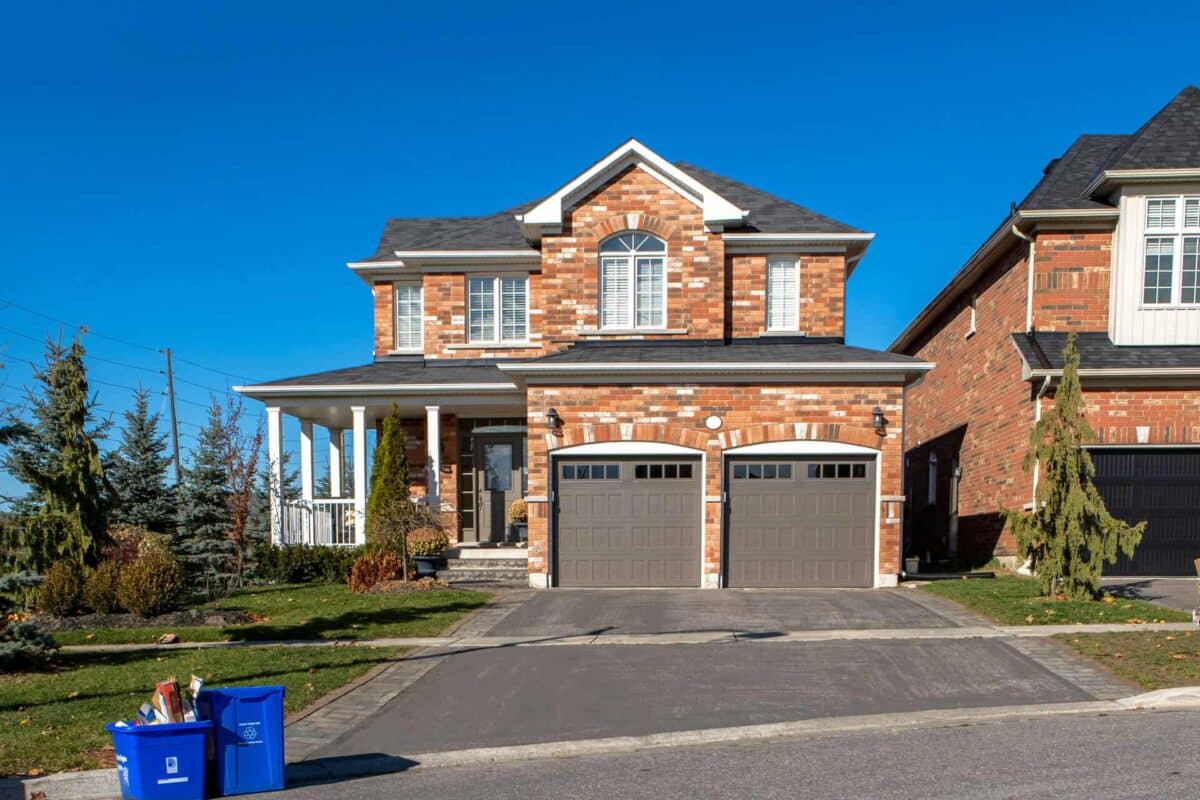
Brick house with two garages, manicured lawn, and recycling bins, illustrating mortgage options under 90% LTV.

Refinance for a better rate.

  • Refinancing your existing loan is a great way to lower your monthly payment, shorten the term of your loan, or reduce the amount of interest that you will pay over the life of your loan.

*Five/One Adjustable-Rate Mortgage (ARM): The Annual Percentage Rate (APR) assumes a Five/One ARM of $100,000 without private mortgage insurance (PMI) for a 30-year term. The APR of 6.369% reflects the initial rate of 5.625% for years 1–5 and the fully indexed rate of 6.625% for years 6–30, and includes a 1% origination fee and 30 days’ interim interest paid at closing. Initial monthly principal and interest of $575.66 for years 1–5. Beginning in year 6, the rate adjusts annually to the 1-Year Constant Maturity Treasury (CMT) plus a margin of 2.50% (fully indexed rate); based on the index value as of September 15th, 2026, the rate would be 6.625%, and the monthly principal and interest would be $632.58 for years 6–30. The rate may increase after the initial five-year period, and your payment may increase. The rate floor is 4.00%. Adjustable rates have an annual cap of 1% and cannot change more than 8% over the life of the loan. The estimated payment does not include taxes and insurance premiums; your actual payment obligation will be greater. Escrow may be required. +97% LTV is available to first-time home buyers; 95% LTV is the maximum for all other borrowers. PMI is not required unless you borrow more than 90% loan-to-value (LTV). This limited-time rate applies to new loans and refinanced loan amounts not currently held by the credit union. Limited to borrowers’ primary or secondary homes located in SC. Excludes attorney, title, tax, recording, survey, pest inspection, and other fees. $625 appraisal and a $10 flood certification are required. Other closing costs may apply. Other property and underwriting restrictions apply. Mortgage loan rates are subject to creditworthiness and credit approval. Not all applicants will qualify. Programs, rates, terms, and conditions are subject to change without notice. Insured by NCUA. ©2026 Greenville Federal Credit Union. All rights reserved.

HOME MORTGAGE DISCLOSURE ACT NOTICE

The HMDA data about our residential mortgage lending are available online for review. The data show geographic distribution of loans and applications; ethnicity, race, sex, age, and income of applicants and borrowers; and information about loan approvals and denials. HMDA data for many other financial institutions are also available online. For more information, visit the Consumer Financial Protection Bureau’s Web site (www.consumerfinance.gov/hmda).</p>

Have a question?

Find the answer faster in our Help Center.

Your Privacy

By clicking “Accept all,” you agree Greenville Federal Credit Union can store cookies on your device and disclose information in accordance with our Cookie Policy.